Member e-Learning 9-19-24 – John
FDX Misses and Getting Hammered Early
Markets gapped strongly higher at the open Thursday. SPY gapped up 1.73%, DIA gapped up 1.39%, and QQQ gapped up a whopping 2.39%. From that point, all three major index ETFs saw volatility in the first hour, followed by a rally that lasted until about 2 p.m., when a modest selloff took over and lasted the rest of the day. This action gave us gap-up, indecisive, Doji-type candles. SPY was a true Doji that printed new all-time high and new all-time high close. DIA gave us a black Spinning Top that also printed new all-time high and all-time high closes. Meanwhile, QQQ gave a white Spinning Top that broke its downtrend line (going back to the all-time high in July) and retested, but did not close above, a resistance line running back through the August 22 high. This all happened on average volume across all three major index ETFs.
On the day, eight of the 10 sectors were in the green, with Technology (+2.73%) out in front of the others leading the rest of the market higher. On the other side, Utilities (-0.21%) and Consumer Defensive (-0.13%) were the only sectors in red. Meanwhile, SPY gained 1.71%, DIA gained 1.25%, and QQQ gained 2.53%. VXX fell 4.33% to close at 47.72 and T2122 climbed back into the top half of its over-bought range at 94.74. At the same time, 10-Year bond yields rose to close at 3.719% while Oil (WTI) popped 1.61% to close at $72.05 per barrel on supply fears caused by Israeli bombing in Lebanon and the Hezbollah Leader saying Israel “crossed red lines” and there would be a reckoning. So, Thursday was basically a re-think of the Fed policy change resulting in a gap higher. After that gap, it was just volatility the rest of the day.
The major economic news scheduled for Thursday included the Weekly Initial Jobless Claims, which came in lower than expected at 219k (compared to the 230k forecast and prior week’s 231k). On the ongoing front, Weekly Continuing Jobless Claims were also down at 1,829k (versus a forecast of 1,850k and a prior week value of 1,843k). At the same time, the Q2 Current Account was lower at -$266.8 billion (compared to a forecast of -$259.0 billion and a Q1 reading of -$241.0 billion). Meanwhile, the Philly Fed Mfg. Index was much better at 1.7 (versus a forecast of -0.8 and much better than the August -7.0 value). At the same time, the Philly Fed Mfg. Employment Index was much higher at 10.7 (compared to August’s -5.7 reading). Later, August Existing Home Sales were lower than predicted at 3.86 million (versus a forecast of 3.92 million and July’s 3.96 million number). At the same time, the August US Leading Economic Index was better than anticipated at -0.2% (compared to a forecast of -0.3% and much better than July’s -0.6% value). Finally, after the close, the Fed Balance Sheet showed a $6 billion decrease at $7.109 trillion (versus the prior week’s $7.115 trillion balance).
After the close, LEN reported beats on both the revenue and earnings lines. However, FDX and MLKN missed on both the top and bottom lines. (FDX missed on earnings by more than 25%.)
In stock news, on Thursday, INTC said it has no plans to divest its majority stake in MBLY. At the same time, BABA accelerated its efforts to compete in the AI market by releasing 100 open-source large language models and text-to-video AI technology. (BABA’s competitors like BIDU are primarily pursuing a closed-source approach.) Later, the Wall Street Journal reported that DIS is dumping the CRM-owned worker collaboration tool Slack after the recent hack that exposed more than a terabyte of DIS data. At the same time, GM’s Cruise unit announced it will begin testing up to five autonomous vehicles in the San Francisco Bay area later this fall. Later, BRKB’s railroad (BNSF) announce it had reached a tentative deal with the SMART union on a 5-year labor contract. At the same time, KO announced plans to invest $1 billion in Nigeria operations over the next five years. Later, TLSA rival NIO announced price cuts on its first car, now starting at $21,210 in China.
Elsewhere, the CWA union announced NYT workers had approved a strike, with 95% voting in favor of a strike. At the same time, NKE announced its CEO (Donahoe) will step down on October 14 and will be replaced by former NKE senior executive Elliott Hill, who had left after 32 years at NKE. (CNBC reported Donahoe was being forced out as the board seeks to restructure the company.) Later, MA announced that they forecast holiday spending will grow by 3% again this year during a shorter-than-usual holiday window. Meanwhile, GOOGL announced that ads will now be able to run, even when a YouTube video has been paused. This annoyance may well just be intended to increase sales of YouTube Premium subscription accounts ($13.99/month) which avoids ads altogether. Later, after the close, the CEO of MASI was ousted after activist investor Politan won two board seats during a shareholder proxy vote. Finally, Bloomberg reported the EU has warned AAPL that it must open up its extremely-guarded iPhone and iPad operating systems to rival technologies OR it will face significant (unspecified) fines. The report says AAPL was given six months to do this before penalties will begin.
In stock legal and governmental news, on Thursday, the SEC announced that MQBKY (investment advisor) had agreed to pay $79.8 million to settle charges of overvaluing collateralized mortgage obligations held in its advisory accounts between 2017 and 2021. At the same time, the Bureau of Land Mgmt. published a key environmental report, which was the last step to approval of IONR’s Rhyolite Ridge lithium mine in NV. (The mine will produce enough lithium for 370k electric vehicles per year. F and TM have both agreed to buy lithium from that mine.) Later, Reuters reported that a criminal investigation is underway at the ET natural gas liquids plant that exploded and has been burning in La Porte TX since Monday. (A body was found in the car that hit the pipeline.) At the same time, the FDA approved ELAN’s skin disease treatment for dogs. After the close, the Anti-Defamation League joined a lawsuit alleging INTC has a hostile workplace and has wrongfully discriminated and terminated a former Israeli employee, after that employee accused two executives of openly posting anti-Semitic propaganda tied to the Israeli-Hamas war.
In miscellaneous news, on Thursday, Reuters reported that pro-Ukraine congressional leaders and the Biden administration are very near an agreement to extend expiration of $6 billion in military aid for Ukraine. The report indicated that the deal would extend the period during which the President us able to drawdown US military supplies and use the $6 billion to replenish. If not extended, the $6 billion expires at the end of the month. Elsewhere, not waiting on the dysfunctional GOP House, the Senate Majority Leader moved a placeholder stop-gap bill through procedural hurdles. This will allow the Senate to vote on a government funding continuing resolution almost immediately, if the House can get one passed and send it to the Senate. Meanwhile, Freddie Mac reported Thursday that the national average 30-year, fixed-rate, conforming mortgage rate dropped to 6.09% (down from 6.20% a week prior).
In Fed rate forecasting, the day following the Fed’s 50-basis-point cut, the Fed Funds Futures market closed while expecting a quarter-point cut in early November and then a half point cut in mid-December. Specifically, 60.9% of trades expect a quarter-point cut in September, with the other 39.1% predicting a half percent cut at that meeting. For December, 29.0% forecast a cut to 4.25%-4.50% (a total of a half of a percent lower than the current rate) while 50.5% expect 4.00%-4.25% (three-quarters of a percent lower than current), and 20.5% of trades predict a cut to 3.75%-4.00% (a full percent lower than current, or in other words, expect two cuts of half a percent during the last two meetings of the year).
Overnight, Asian markets were mixed, but leaned toward the green side with just four of the 12 exchanges in the red in that region. (Note that the Bank of Japan held rates steady.) However, in Europe, we see red across the board at midday after the Bank of England and Norway’s central bank both held rates steady in contrast to the Fed’s big cut Wednesday. The CAC (-0.72%), DAX (-0.86%), and FTSE (-0.49%) lead the region lower in early afternoon trade. In the US, as of 7:15 a.m., Futures are pointing toward a mixed but down start to Friday. The DIA implies a +0.03% open, the SPY is implying a -0.25% open, and the QQQ implies a -0.43% open at this hour. At the same time, 10-Year bond yields are at 3.732% and Oil (WTI) is off 0.43% to $71.64 per barrel in early trading.
The only major economic news scheduled for Friday is Fed member Harker speaking at 2 p.m. There are also no major earnings reports scheduled for either before the open or after the close.
In overnight news, MBGAF (Mercedes Benz) gave a profit warning and lowered its guidance, citing slow sales in China. The CEO of Mercedes promised a sales push in China, presumably meaning a lowering of prices as well as introducing new “products” to the Chinese market. Also, after their bad report, FDX is down more than 12% in premarket trading. Early Friday, CEG announced it will restart the Three-mile Island nuclear power plant and have contracted to sell the power produced to MSFT.
With that background, it looks like the Bears have control early Friday. All three major index ETFs gapped modestly lower and have printed black-bodied candles since then in the premarket. However, all three remain well above their T-line (8ema). So, the short-term trend is still bullish. The mid-term trend is now also bullish with QQQ the laggard but now well over its downtrend line going back to the July all-time high. In the longer-term we still have a strong Bull trend all three major index ETFs. With regard to extension, none of the three major index ETFs are too far extended above their T-lines given the premarket action, but they were getting close as of Thursday’s close. However, the T2122 indicator is back in the top half of its overbought range. So, markets may have room to run either direction, but the Bears definitely have more slack to work with today. With regard to those 10 big dog tickers, eight of the 10 are in the red with the two remaining just barely holding onto green territory. NVDA (-0.87%) and INTC (-0.85%) lead the losses while NVDA and TSLA (-0.72%) lead the dollar-volume traded as usual. GOOGL (+0.16%) is holding up better than the other big dogs. Also, bear in mind that today is Friday, pay day, and also triple witching day. So, prepare your account for potential volatility in the afternoon as well as the weekend news cycle.
As always, be deliberate and disciplined…but don’t be stubborn. If you have a loss, admit you were wrong and take that loss before it gets out of hand. And when the price does move in your direction, always move your stops in your favor and take a little profit off the table. You have to keep the “Legend of the Man in the Green Bathrobe” in mind. In a winning situation, it is NOT HOUSE MONEY you’re betting, it’s YOUR MONEY! There is no reason to keep raising your bet (risk) size just because you’ve had a win. Finally, remember that trading is not a hobby, it’s a job. The gains are real and so is the risk. So, treat it that way. Do the work and follow the process. Stick to your trading rules, trade with the trend, and take those profits when you have them. Do the work!
See you in the trading room.
Ed
🎯 Mike Probst: Rick, Got CTL off the scanner today. Already up 30%. Love it.
🎯 Dick Carp: the scanner paid for the year with HES-thank you
🎯 Arnoldo Bolanos: LTA scanner really works $$, thanks Ed.
🎯 Bob S: LTA is incredible…. I use it … would not trade without it
🎯 Malcolm .: Posted in room 2, @Rick… I used the LTA Scanner to go through hundreds of stocks this weekend and picked out three to trade: PYPL, TGT, and ZS. Quality patterns and with my trading, up 24%, 7% and 12%…. this program is gold.
🎯 Friday 6/21/19 (10:09 am) Aaron B: Today, my account is at +190% since January. Thanks, RWO HRC Flash Malcolm Thomas Steve Ed Bob S Bob C Mike P and everyone that contributes every day. I love our job.
Hit and Run Candlesticks / Road To Wealth Youtube videos
Disclosure: We do not act on all trades we mention, and not all mentions acted on the day of the mention. All trades we mention are for your consideration only.
Free YouTube Education • Subscription Plans • Private 2-Hour Coaching
DISCLAIMER: Investing / Trading involves significant financial risk and is not suitable for everyone. No communication from Hit and Run Candlesticks Inc, its affiliates or representatives is not financial or trading advice. All information provided by Hit and Run Candlesticks Inc, its affiliates and representatives are intended for educational purposes only. You are advised to test any new trading approach before implementing it. Past performance does not guarantee future results. Terms of Service
Member e-Learning 9-19-24 – Ed Carter
Fed Goes Big and After Sleep The Bulls Run
Wednesday was about what we (or at least I) had expected. SPY opened up 0.09%, DIA opened up 0.05%, and QQQ gapped up 0.24%. From there, all three major index ETFs immediately crossed back below the prior close before grinding sideways in a tight range for two hours. Then we saw a modest selloff followed by a modest rally back to the same level waiting on the Fed. At 2 p.m. we had a 5-minute rip upward and volatility followed by a drift higher into Chair Powell’s presser at 2:30 p.m. After Powell started, we sold off the rest of the day. This action gave us black-bodied, Inverted Hammer candles in all three major index ETFs. SPY and DIA printed new all-time highs, while QQQ again retested and closed below its downtrend line running back to Mid-July. None of the three retested or crossed below their T-line (8ema). This all happened on slightly below-average volume in SPY, DIA, and QQQ.
On the day, all 10 sectors were in the red, with Utilities (-0.60%) out in front of the others leading the market lower. On the other side, Healthcare (-0.03%), Financial Services (-0.05%), Communications Services (-0.09%) and Consumer Cyclical (-0.09%) were all clustered as laggards. Meanwhile, SPY fell 0.30%, DIA lost 0.26%, and QQQ lost 0.43%. VXX fell 0.83% to close at 49.88 and T2122 fell slightly again but remains in the middle of its over-bought range at 87.50. At the same time, 10-Year bond yields actually gained to close at 3.704% while Oil (WTI) fell 1.55% to close at $70.09 per barrel. So, Wednesday was all about the Fed. the Bulls get their new all-time highs in the large-cap indexes. However, then traders took profits, afraid to hold too much long risk going into tomorrow’s Fed decision, statement, and press conference.
The major economic news scheduled for Wednesday include August Building Permits, which were stronger than expected at 1.475 million (compared to the 1.410 million forecast and a 1.406 million July reading). At the same time, August Housing Starts were strongly higher at 1.356 million (versus a 1.310 million forecast and 1.237 million July value). This was a 9.6% month-on-month increase. Later, Weekly EIA Crude Oil Inventories showed a bigger than anticipated inventory drawdown at -1.630 million barrels (compared to a -0.200 million barrels forecast and the prior week’s +0.833-million-barrel inventory build). Then, at the close, July TIC Net Long-Term Transactions indicated a net inflow of $135.4 billion.
However, the big news of the day came from the FOMC. At 2 p.m. Fed announced a half-percent rate cut (down to the 4.75%-5.00% range) for Fed Funds. At the same time the Current Q3 Interest Rate Projection was down to 4.4% (down from 5.1%). For the 1st-Year Out Q3 Interest Rate Projection (2025) the average estimate is now 3.4% (down from the prior 4.1%). Meanwhile, the 2nd-Year (2026) Q3 Interest Rate Projection is now 2.9% (down from 3.1%). At the same time, the 3rd-Year (2027) Q3 Interest Rate Projection remained steady at 2.9% (from the previous 2.9% forecast). The Longer-Term Q3 Interest Rate Projection was also 2.9% (which was up a tick from the previous average forecast of 2.8%).
In his press conference, Fed Chair Powell said he does not see the risk of economic downturn as heightened. He said, “I don’t see anything in the economy right now that suggests that the likelihood of a recession, sorry, of a downturn, is elevated.” He continued, “You see growth at a solid rate. You see inflation coming down. You see a labor market that’s still at very solid levels. So, I don’t really see that now.” Powell said that there was “broad support” for Wednesday’s half-point cut. However, Fed Governor Bowman (a hawk) dissented, instead calling for a quarter-point cut. Looking forward, at the moment, the Dot Plots indicate two (of 19) board members feel there should be no more cuts in 2024. At the same time, seven of the 19 think one additional quarter point cut will be appropriate. However, the median view is that two more quarter-point cuts will be needed in 2024. On the other end, one of the 19 feels more than half a percent of additional cut in 2024 will be appropriate.
After the close, SCS missed on revenue while beating on earnings.
In stock news, on Wednesday, GM reached a tentative deal with Unifor (the Canadian version of the UAW union) over its Ontario, Canada plant. At the same time, a day after the Dept. of Justice approved the deal, ALK completed the $1.9 billion acquisition of HA. Later, BA began furloughing thousands of workers via a one week off every four weeks scheme. BA announced this will last for the duration of the strike by 33k of its workers in the Pacific Northwest. At the same time, the UAW announced it is considering multiple US strikes against STLA for breaking the contract promises it made a year ago. (The six-week strike a year ago cost the company $834 million.) Later, ROG announce it will buy a controlling stake in the Toronto Raptor’s NBA team and NHL’s Toronto Maple Leafs from BCE for $3.46 billion.
Elsewhere, the UAW said that they have set a September 26 strike deadline for the F River Rouge complex near Dearborn MI. 500 of the complex’s 6,000 workers would participate if a strike takes place. Later, AMZN announced it is raising the pay of its fulfillment and transportation employees by at least $1.50 per hour (and giving them a free Amazon Prime membership) as the company fights unionization and internal pressure for better pay and conditions. At the same time, GM announced it is offering adapters to its electric vehicle owners that would allow them to use the TSLA network of chargers. Finally, TUP did file for bankruptcy Wednesday as was rumored earlier in the week.
In stock legal and governmental news, on Wednesday, GSK announced it has agreed to settle two lawsuits in CA that had claimed its discontinued Zantac heartburn drug caused cancer. (No financial details were released.) Later, the CEO of GME (Cohen) agreed to pay a $1 million penalty to the FTC for failing to disclose that he purchased $100 million of voting shares in WFC in 2018. (He did so not as an investment, but as a way to influence WFC operations and in pursuit of a board seat.) At the same time, GOOGL won a legal challenge against a $1.7 billion fine from EU antitrust regulators. The court agreed with the regulator, but threw out the fine. The antitrust commission can appeal.
Meanwhile, a separate ruling announced at the same time, went against QCOM as it got the court to trim the fine from $269.07 million to $265.40 million. Later, GOOGL asked a UK tribunal to throw out a $9.3 billion lawsuit alleging the company abused its dominance in the online search market. Back in the US, OCFC agreed to pay a $15.1 million settlement for “redlining” via loan discrimination against Black, Hispanic, and Asian loan applicants between 2018 and 2022. At the same time, a second “Zantac trial,” this one against private German firm Boehringer Ingelheim rather than partners GSK, PFE, or SNY ended in a hung jury. Later, FHN agreed to pay $325k to settle SEC charges in relation to the bank’s recommendations of certain products.
In government funding news, Speaker of the House Mike Johnson brought a six-month government funding extension (continuing resolution) including a completely unrelated MAGA voting restriction rider to a vote. (As instructed and demanded by the GOP’s disgraced Presidential candidate.) It failed by a vote of 202-220, as 14 GOP members voted against the ridiculous electioneering stunt. (The main point of the amendment is requiring people to prove their citizenship before voting. This is stupid since it is already illegal for non-citizens to vote and there are only a miniscule number of such cases ever found. This plan would also not even take effect this election cycle as the GOP imply and would like the public to believe. So, it’s an expensive, unfunded, and difficult to implement solution to a non-problem that would not be implemented when the GOP wrongly claims it is needed. In other words, the GOP is happy to risk the economic impact and disruption of government shutdown for yet another attempt to whip up fear and “other” the groups the GOP sees as “they.”) Even more silly is the fact that the whole bill would be dead on arrival in the Senate. Unfortunately, Johnson and other GOP Congressmen then told reporters that the Republicans have no “Plan B” for government funding. So, this does increase the probability of a government shutdown on October 1.
In miscellaneous news, the SEC unanimously (5-0) voted to approve a rule change to allow exchanges to price stocks in half penny increments. There is no word on when such a change might be implemented. However, NDAQ immediately said it would study the matter, but that it would hurt stock markets in the long run (for unspecified reasons). Elsewhere, the US has sued the owner and operator of the Singapore-flagged ship that hit the Baltimore bridge earlier this year, killing six and causing massive damage. The Dept. of Justice is seeking more than $100 million (just for costs incurred in the recovery, expect other suits to cover rebuilding and economic damages) and are alleging the company cut corners on maintenance to save costs, causing the crash.
Overnight, Asian markets were green across the board. Japan (+2.13%), Hong Kong (+2.00%), and Taiwan (+1.68%) led the region higher on the day. Meanwhile, in Europe, with the minor exception of Portugal (-0.31%) we see the same green picture at midday. The CAC (+2.01%), DAX (+1.52%), and FTSE (+1.20%) lead the region higher in early afternoon trade. In the US, as of 7:30 a.m., Futures are pointing toward a gap higher to start the day. The DIA implies a +1.13% open, the SPY is implying a +1.62% open, and the QQQ implies a +2.07% open at this hour. At the same time, 10-Year bond yields are up to 3.713% and Oil (WTI) is up 0.75% to $71.42 per barrel in early trading.
The major economic news scheduled for Thursday includes the Weekly Initial Jobless Claims, Weekly Continuing Jobless Claims, Q2 Current Account, Philly Fed Mfg. Index, and Philly Fed Mfg. Employment (all at 8:30 a.m.), August Existing Home Sales and August US Leading Economic Index (both at 10 a.m.), and Fed Balance Sheet (4:30 p.m.). The only major earnings reports scheduled for before the open is CBRL, DRI, and FDS. Then, after the close, FDX, LEN, and MLKN report.
In economic news later this week, on Friday, there is no major news, but Fed member Harker speaks. In terms of earnings reports later this week, on Friday there are no earnings reports of note.
So far this morning, FDS reported beats on both the revenue and earnings lines. At the same time, DRI missed on both the top and bottom lines. (CBRL is scheduled to report at 8 a.m.)
With that background, it looks like the Bulls are running this morning. All three major index ETFs gapped higher to start to premarket and have printed larger, white-body candles since then in the early session. SPY and DIA are sitting at new all-time highs again in the premarket. All three remain well above their T-line (8ema). So, the short-term trend is bullish. The mid-term trend is now also bullish with QQQ the laggard gapping well over its downtrend line going back to July. In the longer-term we still have a strong Bull trend all three major index ETFs. In terms of extension, none of the three major index ETFs are too far extended above their T-lines, but they are starting to get close in the early session today. However, at the same time, the T2122 indicator is still in the middle of its overbought range. So, markets have room to run either direction (if one side or the other can find momentum), but the Bears have a little more slack to work with today. With regard to those 10 big dog tickers, all 10 are strongly green so far this morning. AMD (+334%), NVDA (+3.15%), and TSLA (+3.00%) lead the gains while NVDA and TSLA lead the dollar-volume traded as usual. NFLX (+1.52%) is the “laggard” among those 10 bellwethers.
As always, be deliberate and disciplined…but don’t be stubborn. If you have a loss, admit you were wrong and take that loss before it gets out of hand. And when the price does move in your direction, always move your stops in your favor and take a little profit off the table. You have to keep the “Legend of the Man in the Green Bathrobe” in mind. In a winning situation, it is NOT HOUSE MONEY you’re betting, it’s YOUR MONEY! There is no reason to keep raising your bet (risk) size just because you’ve had a win. Finally, remember that trading is not a hobby, it’s a job. The gains are real and so is the risk. So, treat it that way. Do the work and follow the process. Stick to your trading rules, trade with the trend, and take those profits when you have them. Do the work!
See you in the trading room.
Ed
🎯 Mike Probst: Rick, Got CTL off the scanner today. Already up 30%. Love it.
🎯 Dick Carp: the scanner paid for the year with HES-thank you
🎯 Arnoldo Bolanos: LTA scanner really works $$, thanks Ed.
🎯 Bob S: LTA is incredible…. I use it … would not trade without it
🎯 Malcolm .: Posted in room 2, @Rick… I used the LTA Scanner to go through hundreds of stocks this weekend and picked out three to trade: PYPL, TGT, and ZS. Quality patterns and with my trading, up 24%, 7% and 12%…. this program is gold.
🎯 Friday 6/21/19 (10:09 am) Aaron B: Today, my account is at +190% since January. Thanks, RWO HRC Flash Malcolm Thomas Steve Ed Bob S Bob C Mike P and everyone that contributes every day. I love our job.
Hit and Run Candlesticks / Road To Wealth Youtube videos
Disclosure: We do not act on all trades we mention, and not all mentions acted on the day of the mention. All trades we mention are for your consideration only.
Free YouTube Education • Subscription Plans • Private 2-Hour Coaching
DISCLAIMER: Investing / Trading involves significant financial risk and is not suitable for everyone. No communication from Hit and Run Candlesticks Inc, its affiliates or representatives is not financial or trading advice. All information provided by Hit and Run Candlesticks Inc, its affiliates and representatives are intended for educational purposes only. You are advised to test any new trading approach before implementing it. Past performance does not guarantee future results. Terms of Service
Member e-Learning 9-18-24 – Member Rickster
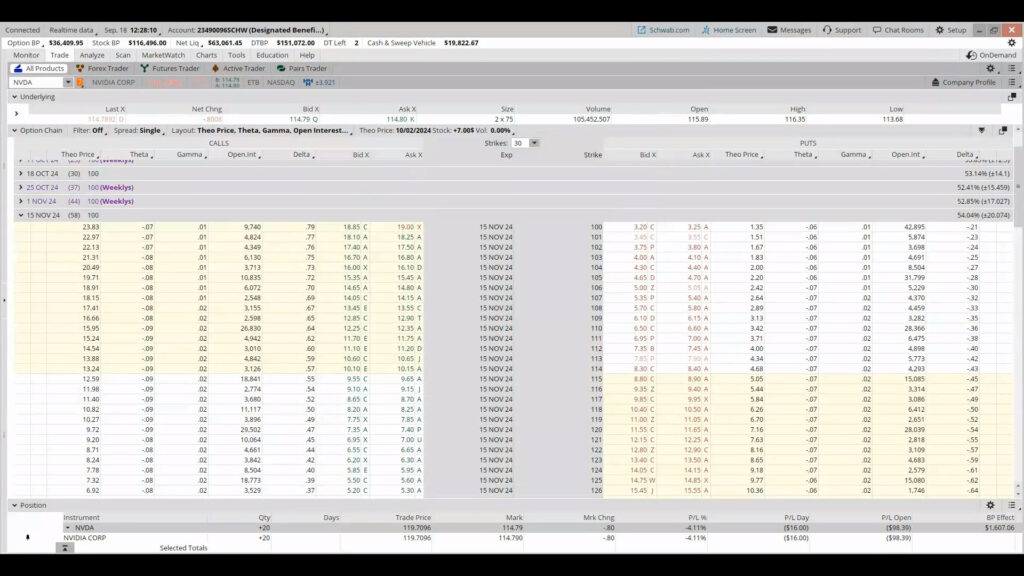
Small Account Trading Using Lower Delta
Fed Pivot Day – Quarter or Half?
Tuesday saw the Bulls go get their new all-time highs and then the Bears fade those gains. SPY gapped up 0.39%, DIA gapped up 0.23%, and QQQ gapped up 0.63%. After that open, all three major index ETFs chopped and then rallied to new highs by mid-morning. Having achieved new all-time highs in SPY and DIA as well as breaking the downtrend line in the QQQ, then the Bears took over to drive the market to lows by early afternoon. From there, all three chopped sideways between their lows and the previous close for the rest of the day. This action gave us black-bodied, indecisive, Spinning Top type candles in all three major index ETFs. The SPY printed a new all-time high and had a gain for the day, but closed slightly below an all-time high close. The DIA did the same, except for closing seven cents below Monday’s close. At the same time, QQQ gapped up and retested its downtrend line reaching back to the all-time high in July. However, it closed back below that line. This happened on less than average volume.
On the day, six of the 10 sectors were in the green again, with Energy (+1.07%) out in front of the others leading the market higher. On the other side, Communications Services (-0.99%) lagged behind the other sectors. Meanwhile, SPY increased 0.04%, DIA lost 0.03%, and QQQ gained 0.05%. VXX gained 2.15% to close at 50.30% and T2122 fell slightly again but remains in the top half of its over-bought range at 92.34. At the same time, 10-Year bond yields gained to close at 3.644% while Oil (WTI) gained 1.75% to close at $71.32 per barrel. So, Tuesday saw the Bulls get their new all-time highs in the large-cap indexes. However, then traders took profits, afraid to hold too much long risk going into tomorrow’s Fed decision, statement, and press conference.
The only major economic news scheduled for Tuesday included the August Month-to-Month Core Retail Sales, which were lower than expected at +0.1% (versus a forecast of +0.2% and the July reading of +0.4%). On the headline number, August Month-to-Month Retail Sales were stronger than expected at +0.1% (compared to a forecast of -0.2% but down a full percent from July’s +1.1%). Later, the August Month-on-Month Industrial Production was much stronger than anticipated at +0.8% (versus a +0.2% forecast and far better than July’s -0.9% value). For the annual number August Year-on-Year Industrial Production was improved at +0.04% versus July’s -0.74% reading. Meanwhile, July Month-on-Month Business Inventories grew by 0.4% (compared to a forecast and June value of +0.3%). On the store front side, July Retail Inventories came in as anticipated at +0.5% (versus the +0.5% forecast and up from June’s +0.3% reading). Then, after the close, Weekly API Crude Oil Stocks showed an inventory build of 1.960 million barrels (compared to a forecasted drawdown of 0.100 million barrels and the prior week’s 2.790-million-barrel drawdown).
In stock news, on Tuesday, BA and union negotiators resume contract talks as the strike against the company continues. (Analysts report the strike is costing BA $100 million per day in lost sales revenue.) At the same time, PM announced it would sell its Vectura Group (asthma inhaler maker) to Molex Asia for $198 million. Later, WMT said it will raise the pay of 100k “Sam’s Club” workers in November. The entry-level pay will go from $15/hr. to $16/hr. (This was part of a labor deal struck three years ago.) At the same time, META announced effective immediately it has rolled out “teen accounts” for its Instagram platform, which automatically puts those under age 18 in an account with extra privacy features and parental controls. Separately, META announced it had banned Russian state media RT for “foreign election interference.” At the same time, the Wall Street Journal reported that JPM is in talks with AAPL about taking over the tech giant’s credit card business from GS.
Elsewhere, Reuters reported that ARKO is planning to sell its convenience store operations (1,500 stores) for around $2 billion. (This is a reversal of company strategy and would leave it with a fuel distribution unit that serves 1,800 independent gas stations and 300 unmanned fueling sites.) Later, Nippon Steel’s CEO (who travelled to Washington to lobby for the deal) told reporters he is now confident the deal to acquire X will be approved “on the merits.” At the same time, MSFT and BLK announced they plan to launch a $100 billion fund to invest in AI infrastructure to build data centers and fund energy projects. Later, after the close, BLNK announced it will lay off 14% of its global workforce (about 100 jobs) by the end of Q1 2025 in a cost-cutting program.
In stock legal and governmental news, on Tuesday, CI-owned Express Scripts sued the FTC, alleging the agency’s recent report stating that prescription middlemen raise the cost of drugs is defamatory. They asked the federal judge to force the rescinding of the report and the recusal of FTC Chair Lina Khan from any decisions involving CI. The FTC said it plans to fight the lawsuit, saying it stands by its report and that three companies (CI, UNH, and CVS) control more than 80% of the pharmacy benefit manager market. At the same time, testimony in the case of the FTC seeking to block KR’s $25 billion acquisition of ACI ended Tuesday. However, a separate trial brought by the WA state Attorney General seeking to block the deal is just in its second day and a second separate trial brought by the Attorney General of CO will begin in Denver on September 30. (The two companies claim to have spent nearly $900 million trying to fight the three cases so far this year.)
Meanwhile, the CFPB published legal guidance intended to stop banks from charging overdraft fees when consumers had not genuinely consented to the practice. (This is often done via “phantom opt-in” agreements buried in fintech (i.e. websites and ATMs). Later, T agreed to pay $13 million to resolve investigations into the data breach of the cloud vendor in January 2023. (The breach exposed the information of 8.9 million T customers.) At the same time, the US Dept. of Justice said it would allow the ALK $1.9 billion acquisition of HA after the airlines agreed to maintain Hawaiian routes, protect frequent flyer rewards, etc. Later, the Dept. of Energy announced it is accepting bids for 6 million barrels of oil for refilling the Strategic Petroleum Reserve amidst low oil prices. After the close, LUNR announced it had been awarded a $4.82 billion contract by NASA for navigation and communications services in the “near space” region.
In other news, the Insurance Institute for Highway Safety announced the results of a month-long study of TSLA’s Autopilot and VLVLY (Volvo) Pilot Assist partial driving automation systems. The study found that drivers were more likely to be distracted when using these driver assistance systems. In fact, it found they were distracted 30% of the time because the driver had been trained that they could focus attention on other matters and only need to nudge the wheel every three seconds to avoid escalation. (It is worth noting that the studied only covered 43 drivers. So, automakers might argue that the sample size is too small. However, 30% is a huge number and this may well end up meaning additional costs added to carmakers in the form of tools that guard against driver abuse of “assistance.”)
In look-ahead news, the Fedwatch tool has shown a growing number of traders are betting on a half percent rate cut today. One months ago, only 25% or interest rate futures bets were for a 50 basis-point cut. One week ago, that had risen to 34%. On Monday that had risen to 62%. Finally, Tuesday night the implied probabilities from interest rate futures trades showed a 63% chance of a half percent cut versus 37% for a quarter percent cut. (There is absolutely no trades expecting a rate hike, no cut, or a bigger than half percent reduction.)
Overnight, Asian markets were evenly split with six exchanges in the green and six in the red. Hong Kong (+1.37%) was by far the biggest winner while Taiwan (-0.78%) and New Zealand (-0.67%) paced the losses. However, in Europe, we see red across the board at midday. The CAC (-0.45%), DAX (-0.11%), and FTSE (-0.66%) lead the region lower in early afternoon trade. Meanwhile, in the US, as of 7:30 a.m., Futures are pointing toward a modestly green start to the morning. The DIA implies a +0.12% open, the SPY is implying a +0.14% open, and the QQQ implies a +0.22% open at this hour. At the same time, 10-Year bond yields are up to 3.668% and Oil (WTI) is down 1.32% to $70.25 per barrel in early trading.
The major economic news scheduled for Wednesday include August Building Permits and August Housing Starts (both at 8:30 a.m.), Weekly EIA Crude Oil Inventories (10:30 a.m.), Fed Rate Decision, FOMC Statement, Current Q3 Interest Rate Projection, 1st-Year Q3 Interest Rate Projection, 2nd-Year Q3 Interest Rate Projection, 3rd-Year Q3 Interest Rate Projection, Longer-Term Q3 Interest Rate Projection, and FOMC Economic Growth Projections (all at 2 p.m.), Fed Chair Press Conference (2:30 p.m.), and TIC Net Long-Term Transactions (4 p.m.) The only major earnings reports scheduled for before the open is GIS. Then, after the close is SCS reports.
In economic news later this week, on Thursday, we get Weekly Initial Jobless Claims, Weekly Continuing Jobless Claims, Q2 Current Account, Philly Fed Mfg. Index, Philly Fed Mfg. Employment, August Existing Home Sales, August US Leading Economic Index, and Fed Balance Sheet. Finally, on Friday, there is no major news, but Fed member Harker speaks.
In terms of earnings reports later this week, on Thursday, we hear from CBRL, DRI, FDS, FDX, LEN, and MLKN. Finally, on Friday there are no earnings reports of note.
So far this morning, GIS reported beats on both the revenue and earnings lines.
With that background, it looks as if markets are slightly bullish in the premarket. The three major index ETFs opened modestly higher and are giving us small, white-bodied candles inside Tuesday’s black Spinning Top. QQQ looks like it wants to retest that downtrend line going back to the all-time high in mid-July. At the same time, SPY and DIA are close enough to make another run at their all-time highs again. All three remain above their T-line (8ema). So, the short-term trend is bullish. The mid-term trend remains mixed (barely) with the QQQ bearish and just below its downtrend line while the others chase clean air at their highs. In the longer-term we still have a strong Bull trend all three major index ETFs. In terms of extension, none of the three major index ETFs are extended above their T-lines yet. However, at the same time, the T2122 indicator remains in the middle of its overbought range. So, markets have room to run either direction (if one side or the other can find momentum), but the Bears have a little more slack to work with today. With regard to those 10 big dog tickers, seven of the 10 are in the green so far this morning. GOOGL (+0.89%) leads the gains. Meanwhile, NVDA (+0.17%) and TSLA (+0.30%) lead, as usual, in the dollar-volume traded.
As always, be deliberate and disciplined…but don’t be stubborn. If you have a loss, admit you were wrong and take that loss before it gets out of hand. And when the price does move in your direction, always move your stops in your favor and take a little profit off the table. You have to keep the “Legend of the Man in the Green Bathrobe” in mind. In a winning situation, it is NOT HOUSE MONEY you’re betting, it’s YOUR MONEY! There is no reason to keep raising your bet (risk) size just because you’ve had a win. Finally, remember that trading is not a hobby, it’s a job. The gains are real and so is the risk. So, treat it that way. Do the work and follow the process. Stick to your trading rules, trade with the trend, and take those profits when you have them. Do the work!
See you in the trading room.
Ed
🎯 Mike Probst: Rick, Got CTL off the scanner today. Already up 30%. Love it.
🎯 Dick Carp: the scanner paid for the year with HES-thank you
🎯 Arnoldo Bolanos: LTA scanner really works $$, thanks Ed.
🎯 Bob S: LTA is incredible…. I use it … would not trade without it
🎯 Malcolm .: Posted in room 2, @Rick… I used the LTA Scanner to go through hundreds of stocks this weekend and picked out three to trade: PYPL, TGT, and ZS. Quality patterns and with my trading, up 24%, 7% and 12%…. this program is gold.
🎯 Friday 6/21/19 (10:09 am) Aaron B: Today, my account is at +190% since January. Thanks, RWO HRC Flash Malcolm Thomas Steve Ed Bob S Bob C Mike P and everyone that contributes every day. I love our job.
Hit and Run Candlesticks / Road To Wealth Youtube videos
Disclosure: We do not act on all trades we mention, and not all mentions acted on the day of the mention. All trades we mention are for your consideration only.
Free YouTube Education • Subscription Plans • Private 2-Hour Coaching
DISCLAIMER: Investing / Trading involves significant financial risk and is not suitable for everyone. No communication from Hit and Run Candlesticks Inc, its affiliates or representatives is not financial or trading advice. All information provided by Hit and Run Candlesticks Inc, its affiliates and representatives are intended for educational purposes only. You are advised to test any new trading approach before implementing it. Past performance does not guarantee future results. Terms of Service
INTC to Split Out Foundry and Big MSFT Buyback
Markets were a bit divergent, but mostly sideways on Monday. SPY opened 0.04% lower, DIA gapped up 0.35%, and QQQ gapped down 0.44%. After that star, all three major index ETFs were more volatile during the first hour, but then ground their way to the side the rest of the day. This action gave is indecisive candles with DIA and SPY on the upside and QQQ down. SPY printed a white-bodied, Hanging Man type candle sitting very near the August highs and even the all-time highs from July. At the same time, DIA gave us a white-body, Spinning Top, candle that printed both a new all-time high and a new all-time high close. Meanwhile, QQQ printed a long-legged Doji Harami type, perhaps indicating it had failed the downtrend line Friday. This happened on below-average volume in all three of the major index ETFs.
On the day, all 10 sectors were in the green again, with Energy (+1.28%) out in front of the others leading the market higher. On the other side, Consumer Cyclical (+0.16%) lagged well behind the other sectors. Meanwhile, SPY increased 0.15%, DIA added 0.59%, and QQQ fell 0.44%. VXX gained just less than one percent to close at 49.24% and T2122 fell slightly but remains in the top of its over-bought range at 94.93. At the same time, 10-Year bond yields fell to close at 3.621% while Oil (WTI) gained 2.65% to close at $70.47 per barrel. So, on Monday the Bulls got their new all-time high in DIA. However, for the most part, it was a “wait and see” day as traders look forward to the Fed rate decision and Chairman’s press conference on Wednesday afternoon.
The only major economic news scheduled for Monday was the NY Fed Empire State Mfg. Index, which came in quite a bit stronger than expected at 11.50 (compared to a forecast of -4.10 and the August reading of -4.70). This was the sixth straight month of increases in this indicator of manufacturing strength.
In stock news, on Monday, BA announced a hiring freeze, paused all non-essential staff travel, and are considering temporary layoffs according to CNBC. This comes after the union leader for the 33k striking BA workers said he thinks “the work stoppage will drag on for some time.” At the same time, the Teamsters Union announced that hundreds of AMZN delivery drivers in NY have joined the union. Later, TGT announced it will hire 100k season employees this year (in-line with the last three years). In addition, TGT announced it start its holiday promotions early, on October 6. At the same time, Bloomberg reported that CG is reviving its plan to IPO its Nouryon chemical business. Later, AMZN CEO Jassy announced he intends to streamline the company, eliminating management layers with a goal of increasing the employee to manager ratio by 15%. He also announced AMZN will require its employees to return to the office five days per week. During a subsequent Q/A session, Jassy also said that AMZN is eliminating a program that let employees work from anywhere for up to four months per year.
Elsewhere, Reuters reported that BX and Vista Equity Partners are in advanced talks and near a deal to acquire SMAR for roughly $8 billion ($56/share). At the same time, an ET natural gas liquids pipeline in La Porte, TX caught fire, knocking out power to nearly 1,000 homes and businesses in the area. After the close, INTC said it plans to set up its Foundry Services unit as an independent subsidiary. (Many traders see this as a potential pre-cursor to INTC potentially spinning off the unit based on recent comments by CEO Gelsinger that INTC is open to considering the sale of some units.) Separately, INTC announced a multi-year, multi-billion per year, deal with AMZN to co-invest in custom chip designs for use in AMZN’s AWS cloud computing services. Also after the close, Bloomberg reported that TUP is preparing to file for bankruptcy as soon as this week. At the same time, MSFT approved a new $60 billion share buyback program and declared a $0.83 Q3 dividend (which is a 10% increase over Q2’s dividend).
In stock legal and governmental news, on Monday, Reuters reported that forty of the world’s leading banks have joined the G-7 pilot digital currency project run by the New York Fed. This list includes JPM, HSBC, UBS, and MUFG. Later, INTC was awarded up to $3 billion to develop a “Secure Enclave” (which are critical component chips used across a variety of weapons and national security products). At the same time, a US District Appeals Court ruled in favor of XOM, CVX, DVN, ET, OXY, PSX, and CLR by ruling against an appeal made by two dozen consumers of their 2020 lawsuit. The court said there was a lack of proof of the companies’ collusion with Russia and Saudia Arabia to cut oil production to keep oil prices higher. Later, an OR state judge threw out a $260 million jury verdict against JNJ related to the company’s talc (which contained asbestos) causing a woman’s mesothelioma. The judge ordered a new trial, saying the plaintiff’s lawyers had committed “egregious errors.” After the close, the UAW union filed unfair labor practices charges with the NRLB against STLA.
In miscellaneous news, on Monday, the US offshore energy regulator announced that 20% of US Gulf of Mexico oil production and 28% of its natural gas output in the area remain offline following Hurricane Francine. Elsewhere, interest rate futures indicated that more traders are expecting a 50-basis-point rate cut on Wednesday. Probabilities of a half percent cut increased from 30% a week ago, to 50% on Sunday to 62% after the close Monday.
Overnight, Asian markets were mostly green. Hong Kong (+1.34%) led eight gaining exchanges higher while Japan (-1.03%) and Shenzhen (-0.88%) led four lower. The picture is even more green in Europe as 12 of the 14 bourses are above break-even at midday. The CAC (+0.57%), DAX (+0.59%), and FTSE (+0.61%) lead the region higher in early afternoon trade. In the US, as of 7:30 a.m., Futures are pointing toward a modestly green start to the day. The DIA implies a +0.19% open, the SPY is implying a +0.25% open, and the QQQ implies a +0.42% open at this hour. At the same time, 10-Year bond yields are down to 3.61% and Oil (WTI) is just on the green side of flat at $70.16 per barrel in early trading.
The major economic news scheduled for Tuesday includes August Core Retail Sales and August Retail Sales (both at 8:30 a.m.), August Industrial Production (9:15 a.m.), July Business Inventories and July Retail Inventories (10 a.m.), and Weekly API Crude Oil Stocks (4:30 p.m.). The only major earnings reports scheduled for either before the open or after the close is FERG prior to the open.
In economic news later this week, on Wednesday, August Building Permits, August Housing Starts, Weekly EIA Crude Oil Inventories, Fed Rate Decision, FOMC Statement, Current Q3 Interest Rate Projection, 1st-Year Q3 Interest Rate Projection, 2nd-Year Q3 Interest Rate Projection, 3rd-Year Q3 Interest Rate Projection, Longer-Term Q3 Interest Rate Projection, FOMC Economic Growth Projections, Fed Chair Press Conference, and TIC Net Long-Term Transactions are reported. On Thursday, we get Weekly Initial Jobless Claims, Weekly Continuing Jobless Claims, Q2 Current Account, Philly Fed Mfg. Index, Philly Fed Mfg. Employment, August Existing Home Sales, August US Leading Economic Index, and Fed Balance Sheet. Finally, on Friday, there is no major news, but Fed member Harker speaks.
In terms of earnings reports later this week, on Wednesday, GIS and SCS report. On Thursday, we hear from CBRL, DRI, FDS, FDX, LEN, and MLKN. Finally, on Friday there are no earnings reports of note.
So far this morning, FERG missed on revenue while beating on earnings. FERG also raised its forward guidance.
With that background, it looks as if markets are bullish again in the premarket. All three major index ETFs opened higher (with QQQ providing the biggest gap up) and have traded modestly bullish from that open. DIA is sitting at another all-time high, SPY is retesting its own all-time high, meanwhile QQQ is back up to retest its mid-term downtrend line stretching back to early-July. All three remain above their T-line (8ema). So, the short-term trend is bullish. The mid-term trend remains mixed (barely) with the QQQ bearish and just below its downtrend line while the others chase clean air at their highs. In the longer-term we still have a Bull trend all three major index ETFs. In terms of extension, none of the three major index ETFs are extended above their T-lines yet. However, at the same time, the T2122 indicator remains in the top end of its overbought range. So, markets have room to run either direction (if one side or the other can find momentum), but the Bears have a little more slack to work with today. With regard to those 10 big dog tickers, nine of the 10 are in the green so far this morning. INTC (+7.13%) is far and away the percentage gainer on the news of the split out of its Foundry business. Meanwhile, NVDA (+0.71%) is, as always, the dollar-volume leader. Only AAPL (-0.17%) lags among the big dogs.
As always, be deliberate and disciplined…but don’t be stubborn. If you have a loss, admit you were wrong and take that loss before it gets out of hand. And when the price does move in your direction, always move your stops in your favor and take a little profit off the table. You have to keep the “Legend of the Man in the Green Bathrobe” in mind. In a winning situation, it is NOT HOUSE MONEY you’re betting, it’s YOUR MONEY! There is no reason to keep raising your bet (risk) size just because you’ve had a win. Finally, remember that trading is not a hobby, it’s a job. The gains are real and so is the risk. So, treat it that way. Do the work and follow the process. Stick to your trading rules, trade with the trend, and take those profits when you have them. Do the work!
See you in the trading room.
Ed
🎯 Mike Probst: Rick, Got CTL off the scanner today. Already up 30%. Love it.
🎯 Dick Carp: the scanner paid for the year with HES-thank you
🎯 Arnoldo Bolanos: LTA scanner really works $$, thanks Ed.
🎯 Bob S: LTA is incredible…. I use it … would not trade without it
🎯 Malcolm .: Posted in room 2, @Rick… I used the LTA Scanner to go through hundreds of stocks this weekend and picked out three to trade: PYPL, TGT, and ZS. Quality patterns and with my trading, up 24%, 7% and 12%…. this program is gold.
🎯 Friday 6/21/19 (10:09 am) Aaron B: Today, my account is at +190% since January. Thanks, RWO HRC Flash Malcolm Thomas Steve Ed Bob S Bob C Mike P and everyone that contributes every day. I love our job.
Hit and Run Candlesticks / Road To Wealth Youtube videos
Disclosure: We do not act on all trades we mention, and not all mentions acted on the day of the mention. All trades we mention are for your consideration only.
Free YouTube Education • Subscription Plans • Private 2-Hour Coaching
DISCLAIMER: Investing / Trading involves significant financial risk and is not suitable for everyone. No communication from Hit and Run Candlesticks Inc, its affiliates or representatives is not financial or trading advice. All information provided by Hit and Run Candlesticks Inc, its affiliates and representatives are intended for educational purposes only. You are advised to test any new trading approach before implementing it. Past performance does not guarantee future results. Terms of Service
Fed Week Starts with Only NY Empire Mfg.
Friday was a bullish but mostly sideways day in the market. SPY opened up 0.12%, DIA opened 0.15% higher, and QQQ opened 0.17% lower. At that point, all three major index ETFs rallied all morning, with DIA reaching the high of the day at noon, SPY hitting its high at 1:40 p.m., and QQQ reaching the high of day at 1:55 p.m. From there, all three went on a modest, undulating selloff the rest of the day. This gave us white-body candles with upper wicks. SPY gapped up for its fifth-straight gain on well-below average volume. Meanwhile, DIA gapped up for a third-straight gain and a backing off from the all-time high retest and did this on above-average volume. At the same time, QQQ gapped down, but closed higher for the fifth-consecutive time and closed just down from its downtrend line going back to the all-time high in early July. QQQ did this on below-average volume.
On the day, all 10 sectors were in the green again, with Basic Materials (+1.63%) and Utilities (+1.61%) well out in front leading the market higher. On the other side, Energy (+0.70%), Communications Services (+0.77%), and Consumer Defensive (+0.78%) were the laggard sectors. Meanwhile, SPY gained 0.52%, DIA gained 0.72%, and QQQ gained 0.45%. VXX fell slightly to close at 48.79% and T2122 jumped higher into the top of its over-bought range at 95.09. At the same time, 10-Year bond yields fell to close at 3.657% while Oil (WTI) gained 0.39% to close at $69.24 per barrel. So, on Friday saw a strong week come to an end on another positive note. For the week, SPY gained 4.01%, QQQ gained 5.94%, and DIA “lagged” while gaining 2.59%. (This was collectively the best week in the market of 2024.)
The major economic news scheduled for Friday included the August Export Price Index, which came in much lower than expected at -0.7% (compared to a -0.1% forecast and July’s +0.5% reading). At the same time, the August Import Price Index was also lower than anticipated at -0.3% (versus a -0.2% forecast and well below the July +0.1% value). Later, Preliminary September Michigan Consumer Sentiment was reported at 69.0 (above the 68.3 forecast and 67.9 August number). At the same time, Preliminary September Michigan Consumer Expectations also came in above the predictions at 73.0 (versus the 71.0 forecast and 72.1 August value). On the future outlook front, Michigan 1-Year Inflation Expectations were reported down at 2.7% (less than the 2.8% forecast and August reading). However, the Michigan 5-Year Inflation Expectations were up to 3.1% (compared to a forecast and August reading of 3.0%).
In stock news, on Friday, UBER announced an expansion of its partnership with GOOGL’s Waymo self-driving taxi unit. The partnership will bring automated ride hailing to Austin TX and Atlanta GA in early 2025. At the same time, Danish DSDVF announced it had agreed to acquire German logistics firm Schenker for $15.85 billion. Later, Bloomberg reported that DBRG is considering the sale of its Southeast Asian unit (EdgePoint Infrastructure) for roughly $4 billion. At the same time, BCSF (Bain Capital) has hired advisers to help in the sale of its British home and car insurer Esure for roughly $1.31 billion). Later, the CFO of BA told reporters the company is eager to return to talks after a strike of 33k workers at its Pacific Northwest plants have shut down production of the company’s best-selling 737 MAX jets. He went on to say the strike now puts delivery targets for 737 MAX planes in jeopardy and will have a financial impact unless settled quickly.
Separately both MCO and Fitch announced they will reduce their credit ratings on BA to “junk status” unless the strike ends quickly. However, no exact definition of “quickly” was provided in either announcement.) On Saturday, DIS and DirecTV announced they had reached a deal that allowed the latter to resume broadcast of ESPN and DIS’s other channels to DirecTV’s 11 million customers after a two-week shutdown. (DirecTV appears to have gotten what they wanted from the negotiation. Specifically, that was the ability to offer DIS channels on an “ala carte” and “skinny package” basis to its customers…as opposed to DIS requiring “all or nothing” offerings of its channels.) At the same time, Reuters reported that T is again in talks with SATS over the merger of their Dish and DirecTV companies. (The initial merger attempt was blocked by the US Justice Dept. in 2002 over anti-trust concerns. However, the entertainment market has obviously changed dramatically since then with streaming and cable market growth.)
In stock legal and governmental news, on Friday, the Washington Post reported that the White House has signaled a delay in making a decision on the Nippon Steel buyout of X. The news comes after Nippon Steel executives flew to Washington to lobby for the deal and the two companies sent a letter to the President urging him to approve the deal or delay the decision until after elections (despite other resistance from both political parties and the Committee on Foreign Investment in the US opposing the deal). Later, Reuters exclusively reported that sources tell it that EU antitrust officials are considering exactly what practices GOOGL will be ordered to end. However, they will not order the breakup of GOOGL (separating ad technology business from the ad sales unit). Meanwhile, a DE judge overruled a Newsmax (planning to IPO in late 2024) motion and ruled the company must face trial for its defamation of Smartmatic (as part of a campaign in support of the disgraced former President’s election lies).
Elsewhere, Bloomberg reported that the EU is planning a final vote on raising tariffs on Chinese EVs on September 25. Later, the State Dept. approved the sale of $7.2 billion of LMT F-35 fighter jets to Romania. Later, the US EPA said it has found that ADM violated federal safe drinking water laws as well as the company’s underground injection permit with leaks at its carbon sequestration facility in IL. At the same time, IEP won the dismissal of a lawsuit alleging the company artificially inflated its share price by issuing “unsustainably high dividends.” Later, after the close, the Dept. of Justice announced WBA had agreed to pay $106.8 million to settle charges it fraudulently billed the US government (Medicare / Medicaid) for prescriptions it never filled. Alsos after the close, Bloomberg reported that INTC has officially qualified for as much as $3.5 billion in federal grants to make chips for the Dept. of Defense. Saturday, HD agreed to pay $1.98 million to CA for over-charging CA consumers via “checkout scanner violations” where checkout scanners charged higher prices than were listed on the item or shelf.
In miscellaneous news, on Friday, China announced it will raise its retirement age for the first time since 1978. The Chinese male retirement age will go from 60 to 63 while women’s retirement will be pushed from 50 to 55. For women in management jobs the increase goes from 58 instead of 55. However, the Chinese government will implement these changes slowly to avoid public unrest. (This seems to be the country’s first real public acknowledgement, without saying it out loud, of the country’s demographic crisis.) Elsewhere, on Saturday, China’s Commerce Minister announced that foreign direct investment in China, covering January through August, had fallen 31.5% year-on-year.
Overnight, Asian markets were mixed but leaned toward the green with just four of the 12 exchanges in the red. Malaysia (+0.84%) and Thailand (+0.78%) led the gainers while New Zealand (-1.00%) and Shenzhen (-0.88%) paced the losses. In Europe, we see a similar picture taking shape with six of the 15 bourses under water at midday. The CAC (+0.02%), DAX (-0.26%), and FTSE (-0.04%) in early afternoon trade. In the US, as of 7 a.m., Futures are pointing toward a mixed start to the day. DIA implies a +0.21% open, the SPY is implying a flat +0.03% open, and QQQ implies a -0.19% open at this hour. At the same time, 10-Year bond yields are down to 3.646% and Oil (WTI) is up almost half a percent to $68.98 per barrel in early trading.
The major economic news scheduled for Monday is limited to the NY Fed Empire State Mfg. Index (8:30 a.m.). here are no major earnings reports scheduled for either before the open or after the close.
In economic news later this week, on Tuesday, we get August Core Retail Sales, August Retail Sales, August Industrial Production, July Business Inventories, July Retail Inventories, and Weekly API Crude Oil Stocks. Then Wednesday, August Building Permits, August Housing Starts, Weekly EIA Crude Oil Inventories, Fed Rate Decision, FOMC Statement, Current Q3 Interest Rate Projection, 1st-Year Q3 Interest Rate Projection, 2nd-Year Q3 Interest Rate Projection, 3rd-Year Q3 Interest Rate Projection, Longer-Term Q3 Interest Rate Projection, FOMC Economic Growth Projections, Fed Chair Press Conference, and TIC Net Long-Term Transactions are reported. On Thursday, we get Weekly Initial Jobless Claims, Weekly Continuing Jobless Claims, Q2 Current Account, Philly Fed Mfg. Index, Philly Fed Mfg. Employment, August Existing Home Sales, August US Leading Economic Index, and Fed Balance Sheet. Finally, on Friday, there is no major news, but Fed member Harker speaks.
In terms of earnings reports later this week, on Tuesday we hear from FERG. Then Wednesday, GIS and SCS report. On Thursday, we hear from CBRL, DRI, FDS, FDX, LEN, and MLKN. Finally, on Friday there are no earnings reports of note.
In overnight news, according to Bloomberg the Dollar fell to its lowest level in nine months, with the move driven by a strong Yen, which reached a 14-month high. Most of these machinations come from speculation on not only the Fed but other central bank rate decisions due this week. Speaking of anticipated central bank decisions, the Fedwatch tool tells us the futures trader positions indicate a 59% probability of a half percent Fed rate cut Wednesday while a quarter-point cut has a 41% chance. This is a 30% shift toward half point in the last week. However, those probabilities are volatile, with 15%-20% moves in a day recently. Finally, PFE published mid-stage trial results in the New England Journal of Medicine which say its experimental cancer treatment ponsegromab has shown positive results treating the weight loss (loss of appetite) that is caused by the cancer. (That condition, cachexia, impacts 9 million people worldwide and results in 80% of them dying within one year due to the inability to withstand the actual cancer treatments.)
With that background, it looks as if markets are undecided early in the premarket. DIA opened slightly higher and has put in a white-body candle with almost no wick as it moves to retest its all-time high in the early session. However, SPY opened down modestly and has printed an indecisive Doji candle in the Premarket. At the same time, QQQ opened flat but has printed a black-body candle with little wick as it is working on a Bear Harami candle at this point. All three remain above their T-line (8ema). So, the short-term trend is bullish. The mid-term trend remains mixed with the QQQ bearish and just below its downtrend line. In the longer-term we still have a Bull trend all three major index ETFs. In terms of extension, none of the three major index ETFs are extended above their T-lines. However, at the same time, the T2122 indicator is back in the top end of its overbought range. So, markets have room to run either direction (if one side or the other can find momentum), but the Bears has a little more slack to work with today. With regard to those 10 big dog tickers, they are split evenly between gainers and losers early, but the dollar-volume trading leaders are in the red, led by NVDA (-1.60%), AAPL (-2.34%), and TSLA (-0.03%).
As always, be deliberate and disciplined…but don’t be stubborn. If you have a loss, admit you were wrong and take that loss before it gets out of hand. And when the price does move in your direction, always move your stops in your favor and take a little profit off the table. You have to keep the “Legend of the Man in the Green Bathrobe” in mind. In a winning situation, it is NOT HOUSE MONEY you’re betting, it’s YOUR MONEY! There is no reason to keep raising your bet (risk) size just because you’ve had a win. Finally, remember that trading is not a hobby, it’s a job. The gains are real and so is the risk. So, treat it that way. Do the work and follow the process. Stick to your trading rules, trade with the trend, and take those profits when you have them. Do the work!
See you in the trading room.
Ed
🎯 Mike Probst: Rick, Got CTL off the scanner today. Already up 30%. Love it.
🎯 Dick Carp: the scanner paid for the year with HES-thank you
🎯 Arnoldo Bolanos: LTA scanner really works $$, thanks Ed.
🎯 Bob S: LTA is incredible…. I use it … would not trade without it
🎯 Malcolm .: Posted in room 2, @Rick… I used the LTA Scanner to go through hundreds of stocks this weekend and picked out three to trade: PYPL, TGT, and ZS. Quality patterns and with my trading, up 24%, 7% and 12%…. this program is gold.
🎯 Friday 6/21/19 (10:09 am) Aaron B: Today, my account is at +190% since January. Thanks, RWO HRC Flash Malcolm Thomas Steve Ed Bob S Bob C Mike P and everyone that contributes every day. I love our job.
Hit and Run Candlesticks / Road To Wealth Youtube videos
Disclosure: We do not act on all trades we mention, and not all mentions acted on the day of the mention. All trades we mention are for your consideration only.
Free YouTube Education • Subscription Plans • Private 2-Hour Coaching
DISCLAIMER: Investing / Trading involves significant financial risk and is not suitable for everyone. No communication from Hit and Run Candlesticks Inc, its affiliates or representatives is not financial or trading advice. All information provided by Hit and Run Candlesticks Inc, its affiliates and representatives are intended for educational purposes only. You are advised to test any new trading approach before implementing it. Past performance does not guarantee future results. Terms of Service
BA Hit By Strike and Fed Rate Cut Size Debate
Thursday gave us another bullish day with much less whiplash than Wednesday. SPY opened 0.11% higher, DIA opened up 0.12%, and QQQ opened up just 0.07% higher. From there, all three major index ETFs meandered sideways for the morning before starting a midday rally that took us to the highs of the day at about 2 p.m. At that point, SPY and DIA ground sideways in a tight range and QQQ had a 15-minute selloff at 2:45 p.m. before following the others sideways in the same tight range. This action gave us white-bodied candles with lower wicks in all three. SPY and DIA both retested their T-line (8ema) and 17ema before rebounding to close at the top of the candle. For its part, QQQ crossed back above its 50sma. This all happened on below-average volume for all three major index ETFs.
On the day, all 10 sectors were in the green, with Basic Materials (+1.82%) well out in front leading the market higher. On the other side, Healthcare (+0.30%) lagged behind the other sectors. Meanwhile, SPY gained 0.84%, DIA gained 0.66%, and QQQ gained 0.98%. VXX fell slightly to close at 48.94% and T2122 jumped back up into the middle of its over-bought range at 88.54. At the same time, 10-Year bond yields rose to close at 3.685% while Oil (WTI) jumped up another 2.79% to close at $69.19 per barrel. So, on Thursday saw the fourth-straight day of gained in SPY and QQQ (also a second-straight for DIA). It was big tech names NVDA (+1.91%), TSLA (+0.74%), AVGO (+3.97%), and META (+2.69%) that drove the SPY and QQQ on dollar-volume.
The major economic news scheduled for Thursday included the Weekly Initial Jobless Claims, which came in a bit higher at 230k (compared to a forecast of 227k and prior week value of 228k). On the ongoing front, Weekly Continuing Jobless Claims were up a bit as anticipated at 1,850k (in-line with the 1,850k forecast and up from the prior week 1,845k reading). At the same time, August Month-on-Month Core PPI was up to +0.3% (versus the +0.2% forecast but well up from July’s -0.2%). On the headline number, August Month-on-Month PPI was also up to +0.2% (compared to a +0.1% forecast and July’s 0.0% value). On the budget front, the August Federal Budget Balance showed a much higher than expected deficit at -$380.0 billion (measured against a forecast of -$285.7 billion and July’s -$244.0 billion reading). Then, after the close, the Fed Balance Sheet was up $2 billion for the week to $7.115 trillion from last week’s $7.113 trillion.
The WASDE Ag report also came out Thursday. It reported an increased 2024 corn crop forecast, up 39 million bushels from last month to 15.2 billion bushels. The silver lining for farmers is that the 55-million-bushel reduction in the beginning inventory number (due to increased usage in ethanol production). Meanwhile, the Soybean forecast was left unchanged at 4.586 billion bushels.
After the close, ABDE and RH both reported beats on both the revenue and earnings lines.
In stock news, on Thursday, LLY announced it will invest $1.8 billion to expand its Irish manufacturing operations. This doubles the company’s investment in those two plants in Ireland. At the same time, GILD reported the results of a Phase 3 trial showing that its injectable HIV prevention drug reduced infections by 96%. (This is far superior to the existing oral pill prevention treatment.) Later, GIS announced it has agreed to sell its North American yogurt business to a French company for $2.1 billion. At the same time, MSFT reported it recovered after an outage of its cloud-based Office365 suite. Later, cable provider CHTR said Thursday that it is adding WBD’s Max and Discovery+ streaming services to its cable packages at no additional charge.
Meanwhile, Reuters reported that GM is in talks to buy electric vehicle batteries (built in the US but made using Chinese company CATL’s technology). The proposed source would be a TTDKY (Japanese company TDK) plant to be located somewhere in the Southeastern US. Later, AAL flight attendants voted to ratify the new 5-year contract with the airline. At the same time, AMZN announced plans to invest $2.1 billion in its Delivery Service Partners program over the next six years. This includes an increase in DSP partner compensation of $660 million over the next year. Later, MA announced it is buying threat intelligence company “Recorded Future” from a private equity firm for $2.65 billion. At the same time, an SEC filing showed that Berkshire Hathaway’s Insurance unit leader (Ajit Jain) sold more than half of his BRKA stock on September 9th.
In stock legal and governmental news, on Thursday, the NHTSA announced it has opened a preliminary investigation into VFS (Vietnam’s VinFast electric car maker) on reports of the company’s “Lane Assist” system malfunctioning. At the same time, a Philly Court jury ruled in favor of BAYRY (Bayer) in a lawsuit alleging the company’s Roundup weed killer caused a plaintiff’s cancer. Later, the FDA approved the first over-the-counter hearing aid software that is intended to be used with AAPL’s AirPod Pro headphones. At the same time, NAVI accepted a CFPB-imposed ban on servicing federal student loans, as well as the $120 million settlement ($100 million in restitution and a $20 million fine). This action was taken over NAVI steering borrowers to delay repayment rather than taking the lower-profit repayment plans those borrowers were qualified to get. Later, Reuters reported that Indian antitrust regulators have found that AMZN and WMT (Flipkart unit) have violated India’s local competition laws by giving preference to selected sellers on their websites. Specifically, the report said that each of the antitrust charges brought against the companies were found to be true.
Elsewhere, the Office of the Comptroller of Currency announced it had entered into a formal agreement prohibiting WFC from expanding its product offerings and requiring the bank to submit action plans to fix its anti-money-laundering compliance programs. (WFC stock was down more than 4% on the news.) Later, the FAA reported that an ALK jet had to abort takeoff to avoid collision with a LUV jet at Nashville’s airport on Thursday. An investigation is underway. At the same time, the Treasury Dept. announced proposed corporate alternative minimum tax rules that would impact 100 large corporations that currently pay an average of 2.6% in taxes (60 of them paying less than 1%). The proposals will generate about $250 billion over 10 years according to Treasury. Later, a US Appeals Court threw out a $564 million jury verdict against BMO over its role in a $3.65 billion Ponzi scheme. At the same time, a federal judge overruled a CFTC decision that had prohibited betting on US elections. So, there will be betting on various election outcomes. After the close, Reuters reported that OXY will receive up to $500 million in support for its carbon capture facility in south TX.
In miscellaneous news, on Thursday, Reuters reported that more than 340k customers were without power in LA following Hurricane Francine. Meanwhile, the CDC reported it still has not identified the origin of a human case of bird flu in MO. (The patient had no known exposure to poultry flocks or dairy herds.) This was the 14th human case so far this year requiring hospitalization and the first with unknown origin. Elsewhere, the SEC announced it is set to vote on new “tick size” rules at a public meeting at 10 a.m. on September 18. The proposed changes would allow stock pricing in increments of less than a penny. (The confusing rule would have four different buckets, with some stocks pricing in penny increments, while others trade in half penny, fifth of a penny, of tenth of a penny increments.)
In what is widely seen as a precursor to Fed action next week, the ECB cut rates by a quarter point again (for the second time this year), lowering its deposit rate to 3.50%. Elsewhere, the Fedwatch tool showed that Feds Fund Futures trades are indicating a increase in the probability of a half percent cut next following the PPI data release. On Wednesday, there was only a 14% probability of a 50-basis-point cut (the other 86% being on a quarter-point cut). However, one day later, that percentage more than doubled to 31% probability of a half percent and 69% expecting a quarter percent cut. In tangentially-related news, mortgage finance agency Freddie Mac said on Thursday that the US average 30-year fixed-rate mortgage fell to 6.20%. That is the lowest rate since February 2023.
Overnight, Asian markets were mixed but mostly green with just four of the region’s 12 exchanges showing red. Malaysia (+0.84%), and Hong Kong (+0.75%) led the gainers while Shenzhen (-0.88%) and Japan (-0.68%) paced the losses. However, in Europe, we see green across the board at midday. The CAC (+0.28%), DAX (+0.52%), and FTSE (+0.30%) lead the region higher in early afternoon trade. In the US, as of 7:30 a.m., Futures are pointing toward a modestly green start to the day. The DIA implies a +0.13% open, the SPY is implying a +0.17% open, and the QQQ implies a +0.03% open at this hour. At the same time, 10-Year bond yields are down to 3.648% and Oil (WTI) is up another 1.13% to $69.75 per barrel in early trading.
The major economic news scheduled for Friday includes August Export Price Index, and August Import Price Index (both at 8:30 a.m.), Michigan Consumer Sentiment, Michigan Consumer Expectations, Michigan 1-Year Inflation Expectations, and Michigan 5-Year Inflation Expectations (all at 10 a.m.). There are no major earnings reports scheduled for either before the open or after the close.
In overnight news, aerospace giant BA’s problems increased even more as workers in the Pacific Northwest (more than 30k workers) rejected the company’s contract offer by a massive 96% vote against and promptly went on strike. This was the first BA strike since 2008 and it completely halts production of the company’s best-selling 737 line of jets. Elsewhere, President Biden proposed a rule change that would prevent low-value shipments (largely made up of Temu and Shein retail packages) from getting special custom exemptions and avoid tariffs on Chinese goods. (The White House estimates that those type of shipment have increased from 140 million per year to more than a billion over the last 10 years.)
With that background, all three major index ETFs opened the premarket just on the green side of flat and have been largely indecisive since that point. All three remain above their T-line (8ema). So, the short-term trend is bullish. At the same time, the mid-term trend remains mixed with the QQQ bearish. In the longer-term we still have a Bull trend in the DIA, SPY, and QQQ. In terms of extension, none of the three major index ETFs are extended above their T-lines. However, at the same time, the T2122 indicator is back in the center of its overbought range. So, markets have room to run either direction (if one side or the other can find momentum), but the Bears has a little more slack to work with today. With regard to those 10 big dog tickers, six of the 10 are in the green this morning, led higher by AMD (+0.68%) and GOOGL (+0.65%). On the other side, TSLA (-0.34%) is the laggard. Normalcy has returned to the pre-market dollar-volume with NVDA having traded about five times as much dollar-volume of stock as the next closest ticker this morning.
As always, be deliberate and disciplined…but don’t be stubborn. If you have a loss, admit you were wrong and take that loss before it gets out of hand. And when the price does move in your direction, always move your stops in your favor and take a little profit off the table. You have to keep the “Legend of the Man in the Green Bathrobe” in mind. In a winning situation, it is NOT HOUSE MONEY you’re betting, it’s YOUR MONEY! There is no reason to keep raising your bet (risk) size just because you’ve had a win. Finally, remember that trading is not a hobby, it’s a job. The gains are real and so is the risk. So, treat it that way. Do the work and follow the process. Stick to your trading rules, trade with the trend, and take those profits when you have them. Do the work!
See you in the trading room.
Ed
🎯 Mike Probst: Rick, Got CTL off the scanner today. Already up 30%. Love it.
🎯 Dick Carp: the scanner paid for the year with HES-thank you
🎯 Arnoldo Bolanos: LTA scanner really works $$, thanks Ed.
🎯 Bob S: LTA is incredible…. I use it … would not trade without it
🎯 Malcolm .: Posted in room 2, @Rick… I used the LTA Scanner to go through hundreds of stocks this weekend and picked out three to trade: PYPL, TGT, and ZS. Quality patterns and with my trading, up 24%, 7% and 12%…. this program is gold.
🎯 Friday 6/21/19 (10:09 am) Aaron B: Today, my account is at +190% since January. Thanks, RWO HRC Flash Malcolm Thomas Steve Ed Bob S Bob C Mike P and everyone that contributes every day. I love our job.
Hit and Run Candlesticks / Road To Wealth Youtube videos
Disclosure: We do not act on all trades we mention, and not all mentions acted on the day of the mention. All trades we mention are for your consideration only.
Free YouTube Education • Subscription Plans • Private 2-Hour Coaching
DISCLAIMER: Investing / Trading involves significant financial risk and is not suitable for everyone. No communication from Hit and Run Candlesticks Inc, its affiliates or representatives is not financial or trading advice. All information provided by Hit and Run Candlesticks Inc, its affiliates and representatives are intended for educational purposes only. You are advised to test any new trading approach before implementing it. Past performance does not guarantee future results. Terms of Service